ECB’s 2027 Digital Euro Pilot Is a Test, Not a Public Launch
The European Central Bank plans to test a beta version of the digital euro with selected payment providers, merchants and central-bank staff. The public won’t take part. The pilot can show how the system handles everyday payments, but it won’t decide whether or when the digital euro will be issued.
- 36 payment service providers were selected from more than 50 applicants.
- The 12-month pilot is planned to begin in the second half of 2027.
- The ECB’s 2029 target is readiness for a possible issuance, not a promised launch.
According to the ECB, the selected providers represent a mix of business models, company sizes and geographical coverage. Selected merchants are also expected to take part, along with staff from the ECB and 19 euro-area national central banks.
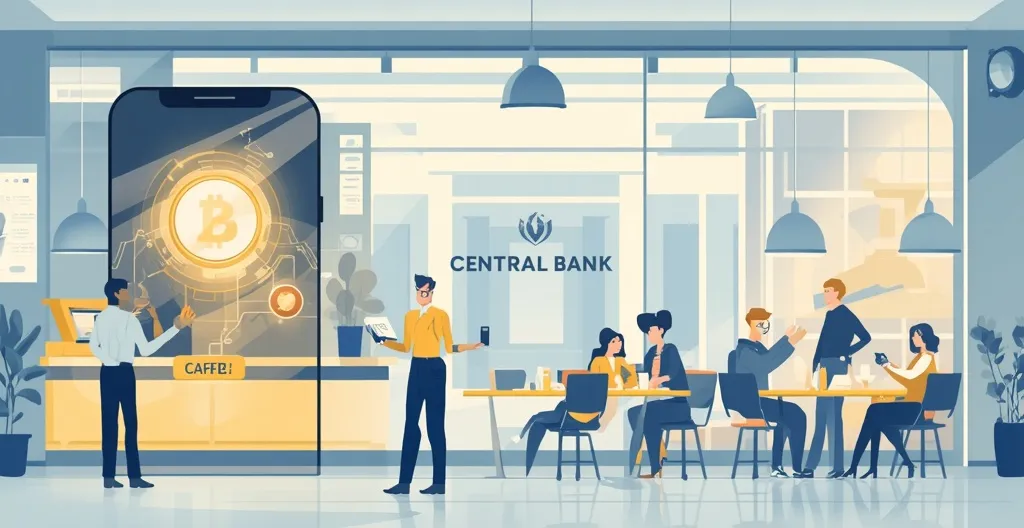
The pilot will test a beta system in practical settings, including in-shop and person-to-person payments. Buying lunch in a cafeteria or paying another person may sound ordinary. That’s the point. A payment system has to work beyond a technical demonstration, for the businesses and people expected to use it.
Payment service providers, or PSPs, help consumers and businesses make or accept payments. Their participation matters because a digital currency needs more than central-bank software. It also needs services people can access and merchants can accept.
A limited test of a proposed public payment option
The digital euro is a proposed central bank digital currency, a digital form of money issued by the central bank. The ECB says it wants to keep central bank money available for everyday payments as technology and payment habits change.
The ECB says the pilot will assess whether the beta system is robust, user-friendly and scalable. A 12-month trial can expose practical problems and help identify improvements. But it can’t, on its own, prove how the system would perform across the euro area at full scale or show that the public wants it.
The ECB selected 36 PSPs from more than 50 applications. That shows interest among the payment providers that applied. It doesn’t prove the public wants a digital euro or that the project has already met its stated aims. Reuters also reported the selection of 36 payment providers.
Merchant selection was still underway in the ECB’s pilot information, which said the outcome was expected by early 2027. So this is a limited test with selected participants, not a public launch. The ECB describes real-life payment situations but doesn’t say whether test transactions will use real funds.
Read the 2029 target carefully
The ECB aims to be ready for a potential first issuance during 2029, assuming the necessary digital euro Regulation is adopted in 2026. That year is an assumption behind the ECB’s planning, not a confirmed legislative deadline or a guarantee that the currency will be issued. The ECB has previously set deadlines for its digital euro work.
The ECB says it would decide whether to issue a digital euro only after the Regulation is adopted. Readiness, approval and issuance are separate steps. Treating them as one scheduled launch would get ahead of the facts.
The ECB presents the project partly as a matter of resilience and strategic autonomy: reducing Europe’s reliance on payment infrastructure provided by companies based outside the region. That’s the institution’s stated rationale, not a proven outcome. Whether a digital euro changes those dependencies in a meaningful way will depend on its final design, adoption and role alongside existing payment options. The ECB has also positioned the project against the growth of private stablecoins.
Design questions remain
The ECB’s pilot information doesn’t specify final privacy arrangements, rules for access to payment data, offline functionality or holding limits. That doesn’t mean no proposals exist elsewhere. It means the pilot details alone don’t answer these consequential questions.
Those choices matter. A digital euro would be public money in digital form, but its usefulness and public acceptance will depend on how it protects users, works in practice and fits alongside cash and private payment services. The pilot can test a beta system. The final rules and design will need scrutiny beyond the trial.
Scam warning: The ECB warns that it will not ask people for money, investments or personal information to take part in the pilot. Treat messages or websites making such requests as suspicious.
Key questions about the digital euro pilot
-
Can the public join the pilot?
No. The planned test involves selected payment providers and merchants, as well as staff from the ECB and 19 national central banks. It isn’t a public launch.
-
Will the pilot use real money?
The ECB describes real-life payment scenarios, including in-shop and person-to-person payments, but its pilot information doesn’t say whether transactions will use real funds.
-
What can the pilot establish?
It can test a beta system’s usability, robustness and scalability in selected settings and help identify improvements. It can’t, on its own, prove performance across the euro area or broad public demand.
-
Does the pilot settle privacy and offline-payment rules?
No. The pilot information doesn’t specify final privacy arrangements, data-access rules, offline functionality or holding limits.
-
Is a digital euro launch confirmed for 2029?
No. The ECB aims to be ready for a potential first issuance in 2029, assuming the Regulation is adopted in 2026. It says it would make a separate issuance decision after adoption.